Market Overview and Significance of the Jewelry And Watch Stores Market
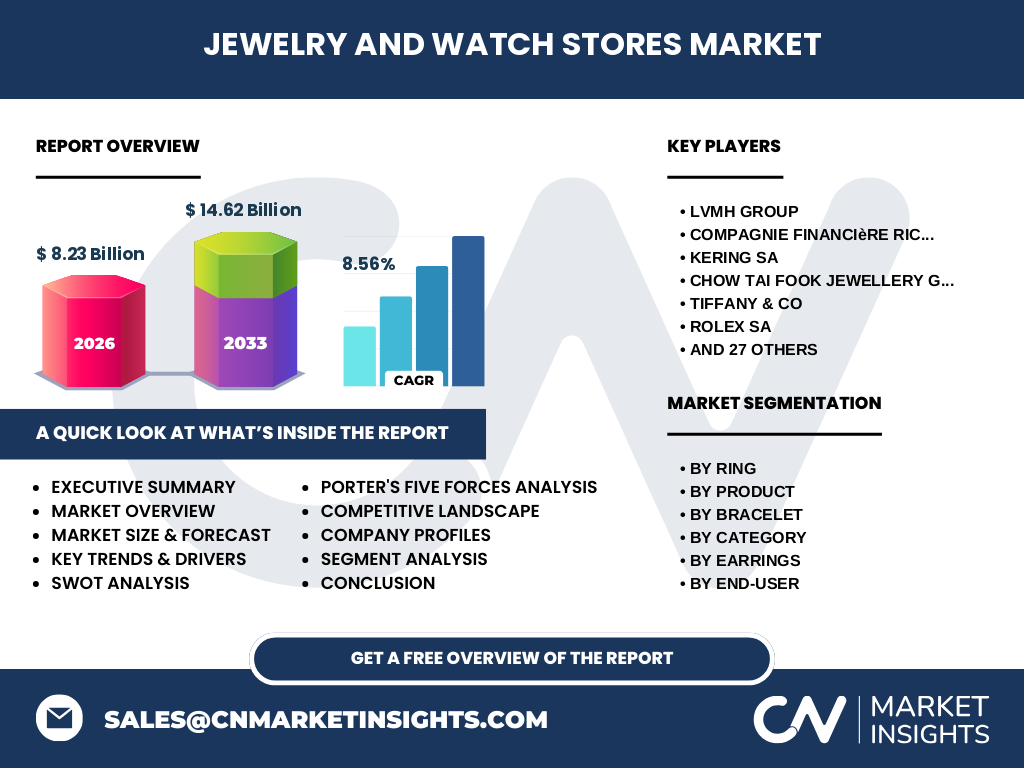
Our analysis indicates that the Jewelry And Watch Stores Market is valued at $8.23 Billion in 2026, serving as a vital retail channel for precious commodities. The industry encompasses specialized brick-and-mortar and digital storefronts distributing high-value items, governed by strict regulatory compliance regarding precious metals verification via bodies like the World Gold Council and international Kimberley Process diamond certifications.
Structural Growth Drivers and Market Restraints
Growth is propelled by rising disposable incomes and luxury gifting traditions, offset by supply chain bottlenecks in procuring ethically sourced gold and platinum. Regulatory burdens from anti-money laundering frameworks and fluctuating precious gem tariffs impose strict operational compliance, testing inventory liquidity across major retail chains.
Emerging Trends Shaping the Jewelry And Watch Stores Market
The shift toward omnichannel retail integration and lab-grown diamond adoption is fundamentally altering inventory strategies. Consumers increasingly demand complete supply chain transparency, favoring brands that utilize blockchain provenance tracking for platinum and gold to verify ethical sourcing.
COVID-19 Impact Analysis and Post-Pandemic Recovery
The pandemic severely disrupted physical retail footprints, causing an unprecedented slump in foot traffic for luxury boutiques. Recovery was accelerated by rapid digital transformation, shifting consumer spend toward e-commerce platforms and virtual try-on technologies for engagement rings and luxury timepieces.
Competitive Benchmarking and Market Concentration
The competitive landscape features a mix of conglomerates like LVMH Group and Compagnie Financière Richemont S.A. alongside specialized horology giants such as Rolex SA and The Swatch Group Ltd. Market concentration is moderate to high at the luxury apex, where heritage branding creates high barriers to entry.
Executive Summary of Key Findings
Our comprehensive research highlights a robust market trajectory, projecting expansion from $8.23 Billion in 2026 to $14.62 Billion by 2033 at a CAGR of 8.56%. Strategic consolidation, omnichannel adoption, and rising demand for bespoke engagement and wedding bands serve as primary catalysts.
Market Forecast and Long-Term Projections
The data projects the Jewelry And Watch Stores Market industry trends to surge, reaching $14.62 Billion by 2033. This expansion, underpinned by an 8.56% CAGR from 2027 to 2033, reflects sustained demand in both mature luxury markets and emerging economies.
Segmentation Analysis Across Product and Material Categories
The sector breaks down by Ring (Engagement Rings, Wedding Bands, Fashion Rings, Signet Rings), Product (Necklace, Ring, Earrings, Bracelet, Other Products including Watches and Brooches), Bracelet (Bangles, Cuffs, Charms, Chains), Category (Branded, Unbranded), Earrings (Studs, Hoops, Drops, Cuffs), End-User (Women, Men, Unisex), Necklace (Chains, Pendants, Statements, Chokers), Price Range (Low, Mid, Luxury), and Material Type (Silver, Gold, Platinum, Diamond).
Regional Market Analysis and Geographic Distribution
Geographic performance varies significantly, with North America and Asia-Pacific leading in total revenue share. Regional growth is heavily influenced by localized cultural affinities for gold and diamond investments, distinct retail real estate costs, and regional luxury tax structures impacting import logistics.
In-Depth Regional Review and Localized Constraints
Asia-Pacific remains a dominant consumption hub driven by bridal traditions, while North America favors branded luxury and customized engagement rings. European markets demonstrate steady demand anchored by heritage Swiss watchmakers and historical jewelry houses operating under stringent EU trade regulations.
Strategic Positioning of Leading Companies
Industry leaders maintain distinct positioning: Chow Tai Fook Jewellery Group Limited commands massive retail volume in Asia, Tiffany & Co dominates branded gifting, and Patek Philippe SA controls ultra-luxury horology scarcity. Meanwhile, firms like Signet Jewelers Limited capture the mid-market bridal segment through extensive mall footprints.
Porter's Five Forces Analysis of Competitive Pressures
Supplier power remains moderate due to consolidated diamond mining cartels, while buyer power is high given extensive online price comparison tools. Threat of substitution is low for high-end precious jewelry, but competitive rivalry among established store chains is intense.
SWOT Analysis of the Industry Landscape
Strengths include high brand equity and strong emotional purchase triggers; weaknesses involve high inventory holding costs. Opportunities lie in digital personalization and emerging markets, while threats include macroeconomic inflation and geopolitical disruptions affecting precious metal supply chains.
Value Chain Analysis from Raw Materials to End-Users
The value chain flows from raw extraction of gold, silver, platinum, and rough diamonds through certified refiners and manufacturers like SHR Jewelry Group, culminating in specialized retail distribution via stores operated by entities such as Bucherer AG or direct-to-consumer digital channels.
Investment Insights and High-Potential Areas
Our analysis indicates prime investment opportunities in omnichannel tech integration, supply chain traceability startups, and brands capturing the growing men's jewelry segment. Capital should target firms successfully bridging physical boutique luxury with seamless digital experiences.
Conclusion and Strategic Takeaways
The Jewelry And Watch Stores Market market size expansion to $14.62 Billion underscores the sector's resilience and adaptability. Success heavily depends on embracing sustainability, ethical sourcing, and omnichannel personalization to engage modern luxury consumers effectively.
Research Methodology and Data Triangulation
Baseline estimates are meticulously triangulated by combining customs trade registry data, primary stakeholder interviews with executives from Swatch Group and Signet, and secondary macroeconomic indicators regarding global high-net-worth individual wealth distribution and luxury retail sales indices.
Scope of the Report and Coverage Parameters
This report covers global retail operations within the Jewelry And Watch Stores Market, analyzing market dynamics from 2026 as a baseline through the forecast period ending in 2033. Excluded from this scope are unverified informal artisan markets and industrial precious metal applications.
Recent Developments and Strategic Corporate Moves
Recent industry momentum features major portfolio expansions by Kering SA, strategic retail partnerships by Boucheron SAS, and sustainability-focused material sourcing announcements by Chopard Manufacture SA, reflecting an industry-wide pivot toward eco-conscious luxury production.